


 Goldman Sachs Forecasts Fed Rate Hike as Inflation Risks Rise
 1 in 3 uni students experience serious financial hardship. Could concession cards for all help?
 Unsustainable – or manageable? We don’t yet know how data centres will impact Australia’s environment
 China’s robots can run faster than Usain Bolt – now they are being prepared for war
 Synthetic data could ease people’s concerns about privacy breaches. But who gets to create it?
 Physicists zoom into the birth of cosmic rainstorms with new CERN study
 Banking scandal rocks Brazil’s politics and the country’s presidential election in October


 Add as a preferred source on Google
The increased industrial funding costs of China are likely to have a toll on eroded profit margins. Manufacturing production and revenues are projected to be under stress given sluggish domestic demand and the constant slowdown in total investment growth. We have already forecasted a lot of shortcomings and risky economic numbers for Chinese growth as China is scheduled to release the official manufacturing PMI for April on 1 May.
The GDP growth slowing to 7% as Chinese Manufacturing sector likely still under pressure will set off more policy easing to avert crumbled growth. We consider policy measures, especially monetary policy easing in the near future may have to gradually boost to the economy.
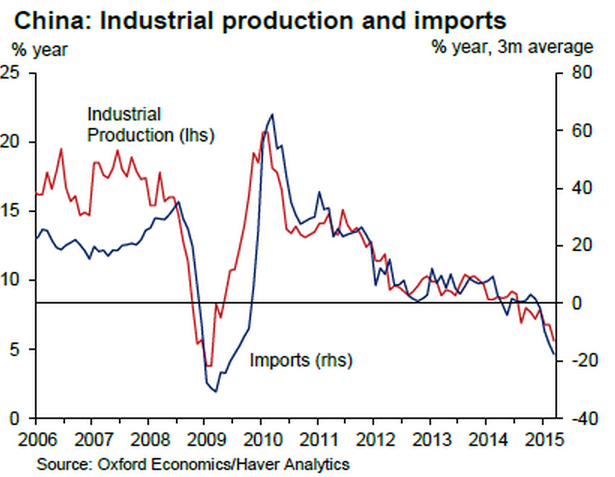
We therefore expect the manufacturing PMI to recover in H2-2015. We expect it to have moderated to 50.0 from 50.1 in March, reflecting still-weak underlying momentum in the manufacturing sector. In the chart, it can easily be figured out how import volumes are directly proportionate to industry production. This explains us to make out the slump in raw material costs have had the adverse impact on its currency, and it's likely to persist. CNY to dollar trading at 6.1935 (22:46 GMT).

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
Chinese growth hopes only on monetary easing
Friday, April 24, 2015 11:53 AM UTC
Editor's Picks



- Market Data
Most Popular




