


 JPMorgan Sees ECB Raising Rates to 2.75% in December
 Goldman Sachs Forecasts Fed Rate Hike as Inflation Risks Rise
 Jefferies Names 6 Top India Stock Picks Across Key Sectors
 Citi Sees Signs of Shift in Global Currency Policy
 Gold Surges Past $4400 on Crude Oil Rally; Bullish Trend Dominates
 Hormuz Shipping Slows as Iran Threats Lift Oil Risks


 Add as a preferred source on Google
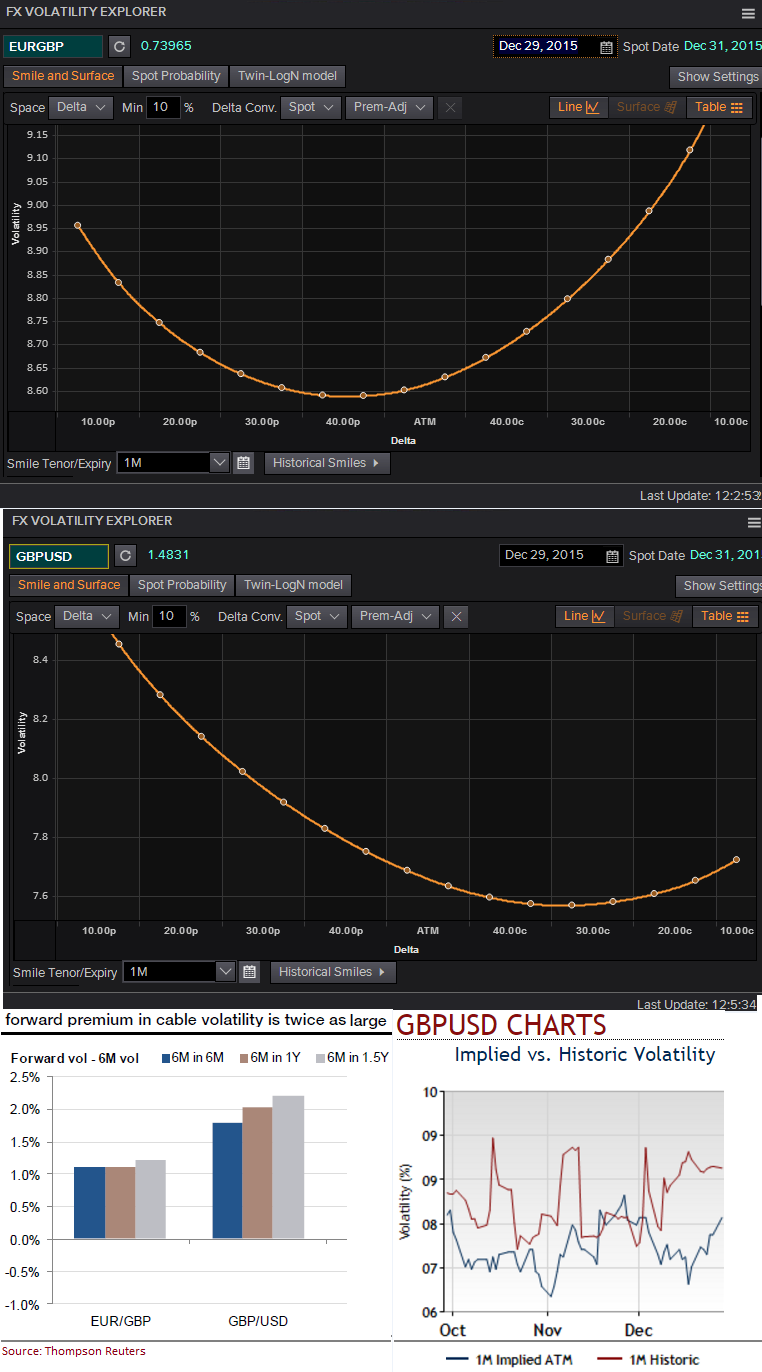
Even if pound sterling volatilities are not trading at historical highs, the FX options market is already heavily positioned upon the Brexit risk.
GBP/USD would fall more than the EUR/GBP would rise in a Brexit scenario. However, this does not imply that the optimal hedging solution is expressed in cable.
Ruthless downgrading UK growth projections would severely hamper sterling.
Capital outflows accelerated by a dismal investment outlook would worsen the UK's external position (the current account deficit has reached a record high of 5.1% of GDP) and fuel a negative GBP spiral, as the economy relies on capital inflows.
EUR/GBP volatility has been discounting a fair amount of euro risk since June, as it has been trading over cable since then.
This is a significant and seemingly lasting regime change, as cable volatility had been more expensive most of the time previously.
Nevertheless, counter-intuitively, the fact that EUR/GBP options currently integrate both European and UK risks makes them a more attractive hedge than cable options.
This is because the real cost of the hedge is reflected in the forward volatility, since the referendum will not be held before autumn 2016.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
EUR/GBP/USD IVs, well positioned OTC and Brexit pressures in H1 2016
Tuesday, December 29, 2015 1:11 PM UTC
Editor's Picks



- Market Data
Most Popular




