


 Europe can’t achieve space sovereignty alone. Here’s why
 AI is supercharging money scams – here’s what you can do to protect yourself
 Unsustainable – or manageable? We don’t yet know how data centres will impact Australia’s environment
 China’s robots can run faster than Usain Bolt – now they are being prepared for war
 Banking scandal rocks Brazil’s politics and the country’s presidential election in October
 Gold Slides to $4,262 as Hawkish Fed Rate Hike Triggers Technical Breakdown
 Goldman Sachs Forecasts Fed Rate Hike as Inflation Risks Rise


 Add as a preferred source on Google
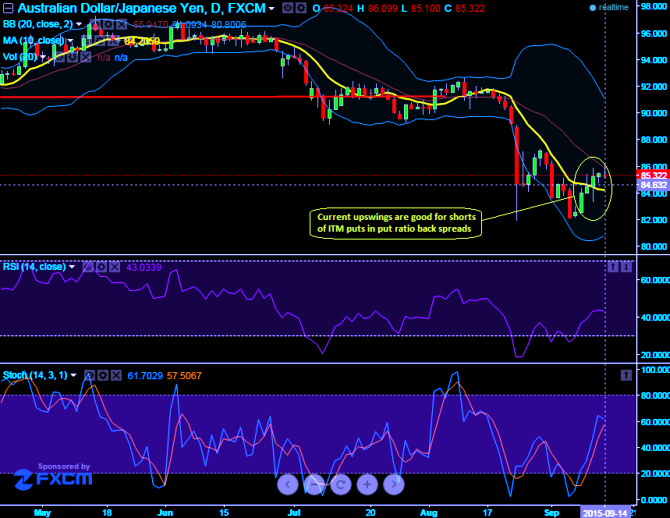
Those who have AUDJPY put ratio back spread, that shorting in the money puts while constructing put ratio back-spreads are functioning well as the pair has been showing upswings from last week, it has spiked up to 86.009 levels, so that the current shorts would go worthless and entire premiums can be spared as absolute profits.
But these shorts would always be at risk of exercise if the market tumbles, but you have two advantages regardless of swings by improving odds in its positions as explained below.
The implied volatility of near month ATM calls are perceived almost close to 24.21% which is quite higher side but good for prevailing shorts while using vega spreads we can neutralize IV effects and participate in upcoming short term downswings.
Firstly, observing maximum tenor on long side: Giving a longer time to expiration for long sides, any abrupt drastic moves on the downside so that assignment can be covered by the long puts.
Secondly, time decay advantage: Using near month contracts or contracts shorter tenor on short side signifies the importance of entering the position when IV is lower than average but AUDJPY IV is seen at 24.21% which is quite higher side (due to data season), so let us keep maturity on short side as normal as near month contract period. Time decay and implied volatility work in your favor on the short puts.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
FxWirePro: Shorts of AUD/JPY PRBS on job amid intermediate uptrend
Monday, September 14, 2015 6:26 AM UTC
Editor's Picks



- Market Data
Most Popular




