


 Ethereum Whale Moves $15.95M ETH to Kraken After Nine Years
 Cardano Hits Five-Year Transaction Record as ADA Price Falls
 Bitcoin Price Drops as US Dollar Hits 18-Month High
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 DeFi Development Adds 22,070 SOL to Solana Treasury
 U.S. Banks Report Strong Q4 Profits Amid Investment Banking Surge
 NEAR Price Surges 11% as Trading Volume Doubles
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 2025 Market Outlook: Key January Events to Watch
 AI Crypto Payments Surge to 138 Million Transactions on Base
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Mexico's Undervalued Equity Market Offers Long-Term Investment Potential
 Urban studies: Doing research when every city is different
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Ripple Partners With DriveWealth to Expand RLUSD Settlements


 Add as a preferred source on Google
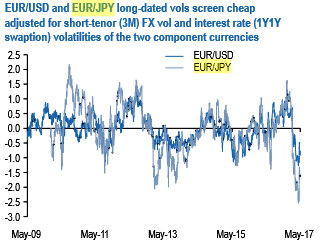
A by-product of the violent de-pricing of French election risk after the first round outcome is that back-end (1Y-2Y) EURUSD and EURJPY vols have crashed to near 2014 lows (refer above chart). This event-related compression comes on the heels of generalized pressure on long-expiry vols across currencies this year due to a mix of Trump-related risk premium squeeze and vol-supplying hedging flows from Japanese importers, European corporates (typically airlines) and the like.
The direction of the vol move appears appropriate given the passage of a potentially disruptive event risk, especially in EURUSD where Euro-rallies have rarely if ever, proven volatile. Yet value becomes the overriding concern once vols fall below certain thresholds, and we believe we are close to those levels seeing how both EURUSD and EURJPY long-dated FX vols are both undershooting meaningfully after adjusting for short-dated FX vol and interest rate (swaption) volatility in the two pairs (refer above chart).
Nominal levels appeal too: EURUSD 2Y vol sub-8, in particular, is in the bottom decile of all available history; EURJPY 2Y vol sub-10 is a relatively more common historical phenomenon but strikes us as the relatively more rewarding hold of the two given (a) the potential for yen to generate volatility in either direction (equity market weakness amid yen strength; structured product effects can create vega demand if the yen weakens materially) and (b) the scope for re-pricing due to not only a surge in Euro and Yen-vol legs individually but also a breakdown of the historically elevated correlation between them (refer above chart) in a classic deleveraging episode.
Triggers for mean-reversion are difficult to anticipate, but appear more likely to be non-European in source assuming polls once again turn out to be correct about the likelihood of a Macron presidency; spillovers from China/commodity market stress and/or US policy volatility (BAT reinstatement, more aggressive than anticipated Fed hikes) are the most likely culprits.
For investors constrained from active delta-hedging of vanilla straddles, volatility swaps and FVAs are viable alternatives, the latter in particular suited as low bleed long vega portfolio hedges along flat vol curves (EURUSD 1Y ATM 7.80, 2Y ATM 7.85; EURJPY 1Y ATM 9.7, 2Y ATM 9.9).







