


 XRP Price Drops 3% Despite Ripple-Backed Evernorth Nasdaq Debut
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Binance to Shut Down Crypto Mining Pool Services on November 10
 Solana Alpenglow Upgrade Set for October 21: What It Means for SOL
 U.S. Banks Report Strong Q4 Profits Amid Investment Banking Surge
 Gold vs Bitcoin: Investors Eye Inflation Hedge as Crypto Adoption Grows
 Morgan Stanley Predicts $10 Trillion RWA Market by 2030
 Pi Network Price Eyes $0.10 Ahead of Protocol 28 Upgrade
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 Monero Price Holds $515 Support as XMR Eyes $545 Breakout
 Most Americans Oppose Election Betting on Prediction Markets, Poll Finds
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 2025 Market Outlook: Key January Events to Watch
 UNCX Network Hack Drains $86K From Ethereum Token Pool


 Add as a preferred source on Google
Demand/Supply equation: On the demand side, investment grade retail funds saw an inflow of €800mm (0.6% of AUM) last week. This was a reduction from the record inflows of €1.6bn last week. While last week saw a solid €10.7bn of investment grade issuance from sixteen new deals, picking the pace up from last week. High yield continued to see a steady pace of issuance in the primary markets with €2bn from five new tranches. We expect primary markets to remain open next week, before effectively shutting for the holidays from 11th December.
Hedge against a double hit risk: Buy straddles on EUR 15y30y to be long vol with a positive vol rolldown.
Rationale: trade the core view and hedge the pain. We expect yields to de-anchor in 2018. Yet, various risk scenarios could prevent rates from taking off. The risk of an equity market correction is one of them. If coupled with lower equity prices and wider credit spreads, even a limited decrease in rates would be a pain scenario for various institutional investors, and especially so for pension funds and insurers.
The IMF highlights the vulnerability of lifers to market and credit risks. A sharp fall in risk asset prices combined with a flight to high-quality sovereign bonds would amount to a double hit on insurers and PFs balance sheets.
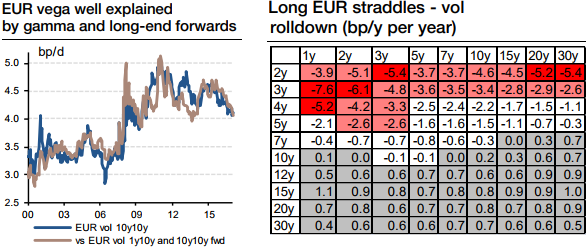
Implementations: buy EUR bottom-right vega EUR vega is typically well explained by short expiry vol and long-end forward rates (refer above table and graph). The 1y10y vol and the 10y10y forward rate account for 83% of the 10y10y vega moves since 2000. The same model is valid for 7y30y or 15y30y. Higher gamma vol drives vega up, but higher long maturity forwards drive vega down. Vega would follow gamma up in a bond sell-off, and especially so if the long-end of the curve bear-flattens. But vega would also move up in a flight-to-quality scenario bull-flattening the EUR curve – even if gamma vols do not spike significantly. So long EUR vega positions are a good hedge against such a debacle risk.
The execution: long vol strategy with positive vol rolldown Long positions in EUR bottom-right vega benefit from a positive vol rolldown (refer above graph). They are hence attractive as strategic vol longs. For instance, the vol rolldown finances roughly 15% of theta in a long 7y30y straddle position and almost 60% of theta in a long 15y30y, making the overall rolldown much less penalizing than for the 5y5y benchmark point (refer above graphs). For the 7y30y, theta cost is completely financed if the 7y30y vol increases in one year’s time by 4.5bp/y (i.e. 0.28bp/d), i.e. moves back to levels seen in 1H 2017. The corresponding breakeven move for the 15y30y vol is only 1.7 bp/y (0.11bp/d). Courtesy: SG







