


 RBA Says ASX Still Falls Short on Governance and Risk Controls
 US Gas Market Poised for Supercycle: Bernstein Analysts
 Mexico's Undervalued Equity Market Offers Long-Term Investment Potential
 Fed Unveils Stablecoin Rules Under GENIUS Act
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 RBI Raises Repo Rate to 5.50% in Hawkish Shift on Inflation Risks
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 Philippines Current Account Deficit Seen at $19.1 Billion in 2026
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 ECB May Stop Rate Hikes After December, Capital Economics Says
 Fed May Resume Rate Hikes: BofA Analysts Outline Key Scenarios
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close


 Add as a preferred source on Google
The US Federal Reserve maintained monetary policy unchanged last night, as broadly anticipated. The accompanying statement was a little more upbeat than before, noting the improvement in consumer and business sentiment. Importantly, though, there was no strong signal of a near-term hike. Domestically, the House of Commons voted to provide the government the ability to trigger Article 50 to start EU withdrawal negotiations by the end of March.
The Bank of England unanimously announces no change in policy today, leaving rates at 0.25% and the planned total stock of asset purchases at £445bn, and maintain the ‘neutral’ bias adopted in the November Inflation Report.
Notably, Governor Carney’s speech on 16 January repeated that monetary policy can respond “in either direction”, with the MPC for the moment choosing to tolerate a period of rising inflation. The data continue to bear out the UK economy’s post-referendum resilience, while further rises in inflation are coming down the tracks.
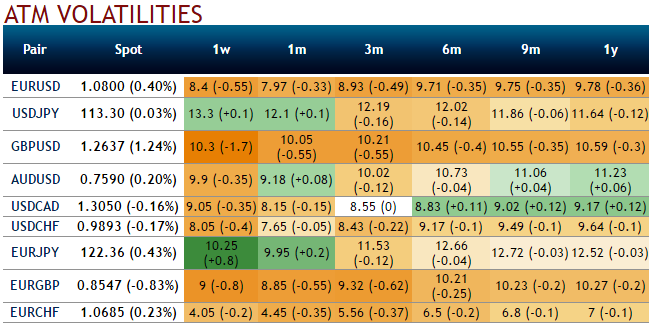
The UK would pursue a different future outside Europe, but the removal of uncertainty around the British stance should prove bearish for GBP volatility. Please be noted that the IVs of GBP crosses (especially EURGBP) has been reducing despite series data, such as the UK PMIs, BoE monetary policy. Accordingly, we’ve devised below option strategy.
Option-trade recommendations: (Writing a strangle)
For those whose foresee non-directional that is existed in this pair from the last couple of months or so to prolong in reducing IV scenario, prefer to remain in the safe zone, we recommend shorting a straddle considering IV shrinks.
Thereby, one can benefit from certain returns by shorting both calls and puts.
Thus, short 7D (0.5% OTM striking) put and (0.5% OTM striking) call simultaneously of the same expiry (preferably, short term for maturity is desired).
The strategy is likely to derive the maximum returns as long as the underlying EURGBP spot FX price on expiry keeps trading between 0.85 and 0.86 levels only as both the instruments have to wipe off worthless. So that the options trader gets to keep the entire initial credit taken as profit.







