


 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 Gold Prices Fall Amid Rate Jitters; Copper Steady as China Stimulus Eyed
 DeFi Development Adds 22,070 SOL to Solana Treasury
 Polygon Labs Completes Coinme Acquisition, Expands U.S. Payments
 Fed May Resume Rate Hikes: BofA Analysts Outline Key Scenarios
 AI Crypto Payments Surge to 138 Million Transactions on Base
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 China's Refining Industry Faces Major Shakeup Amid Challenges
 Solana Alpenglow Upgrade Set for October 21: What It Means for SOL
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 XRP Price Drops 3% Despite Ripple-Backed Evernorth Nasdaq Debut
 Cardano Hits Five-Year Transaction Record as ADA Price Falls
 Dogecoin Price Rebounds as DOGE Defends $0.08 Support
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 Wall Street Analysts Weigh in on Latest NFP Data
 2025 Market Outlook: Key January Events to Watch
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One


 Add as a preferred source on Google
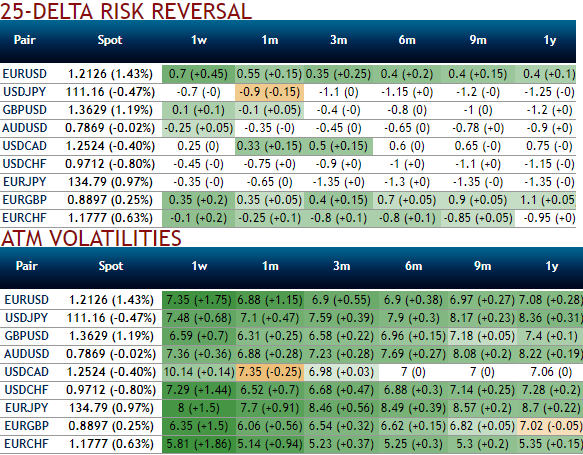
It is expected that EURUSD to gradually spike and approach the 1.23 level by the mid-year point. There continues to be the wide gulf between the European and US equity markets in terms of liquidity and gap between FX volatility. Not only are the cash markets much deeper in terms of daily turnover, but the derivative markets are also dominated by different drivers altogether. The reflections of structured products on volatility, skew, and dividends in Europe is much more pronounced compared to the US which has a much deeper flow market.
The currency market has been acting as the adjustment factor between countries positioned at different parts of the economic cycle clock built. It has been one of the few assets on which carrying long volatility positions has not been a constant pain. It has also led to a dramatic reversal in the correlation regime, leading to some significant discounts on equity options contingent to currency levels.
Tails of 2018:
• Faster Fed tightening, dollar funding shortage
• US Mid-term elections: Republican defeat
• Euro and US inflation relapse
• ECB buys €30bn pcm between Jan-18 and Sep-18, then tapers to €10bn until Dec-18, QE programme ends in 2018, first-rate increase mid-2019
• Correction in equity and credit valuations, house prices
• China de-leveraging, trade disputes, armed conflict
• Bank of Japan ends QE
• Central bank policy mistake, intervention
Bullish scenarios:
Positioning for the end of QE by the ECB should be bullish EUR initially
But not if eurozone interest rates reach no inflection point
Pricing in a peak in US interest rate cycle probably more conducive to tighter Euribor/USD libor spread
After the tax bill, a “lame duck” US president?
Last three US mid-term elections resulted in losses for the president’s Party
US 2018 mid-terms will be held in November
Bearish scenarios:
ECB trapped as inflation and wages continue to disappoint
Italian election brings downside risk, remember 2013
Real rate differentials are moving back in favour of the USD
Eurozone nominal GDP growth set to slow next year (ECB Dec-18 forecast)
US nominal growth to pick up in 2018 (Fed Dec-18 forecast)
EUR CFTC positions at historical high already
Well, all these fundamental developments are factored in EURUSD OTC markets.
Let’s glance at sensitivity tool and risk reversals that indicate mounting changes in the hedging sentiments in next 1m-1y tenors for bullish risks of the underlying spot FX prices.
This sentiment is substantiated by the positively skewed IVs of these tenors that have been signifying the hedgers’ interests of both OTM calls and OTM puts. Hence, this means that the ATM instruments have likelihood of expiring in-the-money within their respective tenors. Courtesy: JPM







