


 BofA Raises Coinbase Stock Target to $203 on Stablecoin Growth
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Mexico's Undervalued Equity Market Offers Long-Term Investment Potential
 Sector Spotlight: Data Availability and Storage Lead 24-Hour Market Gains
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 U.S. Banks Report Strong Q4 Profits Amid Investment Banking Surge
 Stellar Leads RWA Tokenization Growth With $36.4M Inflow
 US Dollar Surge Tests Bitcoin as Fed Rate Bets Rise
 China Shuts 670 Banks as Bitcoin Eyes Financial Risks
 BOJ Set for 25-Basis-Point Rate Hike as Yen Weakness Fuels Inflation
 Yen in Focus as BOJ, Fed Rate Hikes Reshape Currency Markets
 Wall Street Analysts Weigh in on Latest NFP Data
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 RBI Raises Repo Rate to 5.50% in Hawkish Shift on Inflation Risks
 RBA Hikes Interest Rate to 4.60% as Inflation Risks Rise


 Add as a preferred source on Google
RBA maintains status quo to leave its cash rates unchanged at 1.50%, our outlook on the Aussie central bank is to remain on hold throughout 2018, and this is anchoring short-maturity interest rates and should keep 3y swap rates in a 1.80% to 2.30% range, as long as core inflation remains below 2%. Longer maturity rates will largely follow US rates.
Stay long EURAUD and EURNZD as de-synchronized central bank policy cycles, sensitivity to protectionism-inspired risk market stress and medium term valuations continue to underpin our constructive stance on EURAUD and EURNZD.
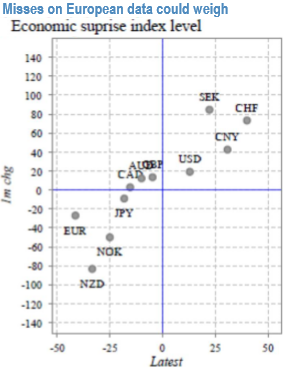
We would have preferred to see a more forceful de-coupling of the Euro from the commodity bloc as trade anxieties mounted this week, but were frustrated by the co-incidence of weaker-than-expected European PMIs. The downward inflection in the European data cycle, albeit at impressively high activity levels, bears close watching as a tactical risk to EUR longs.
Negative data surprises (refer 1st chart) have forced our economists to lower their sights on 2Q’18 growth from 3% to 2.5% QoQ SAAR and pencil in a short taper in 4Q’18 instead of QE ending in September as earlier envisioned.
EUR now features as a sell within our rule-based economic momentum framework as a result of this forecast revision and some trimming of heavy spec longs in the near-term should not come as a surprise.
For EURAUD and EURNZD, the offset is that antipodean data and policy developments over the past two weeks did little to persuade us that shorts in these currencies require a re-think. In Australia, a weak labor market report re-highlighted risks to an over-leveraged household sector, and RBA minutes appeared to edge lower its views on potential growth in a continuation of the slightly dovish strain of commentary from the Bank in recent weeks.
In New Zealand, the 4Q real GDP print came in below consensus expectations and was explicitly noted in this week’s RBNZ statement.
Growth appears to have peaked for the cycle and is likely to fall short of the RBNZ’s +3% forecasts.
Policy rates in both countries, particularly Australia, have substantial room to fall to re-align with the serial disappointment in real activity in recent months (refer 2nd chart); our core thesis is that this should increasingly exert a greater influence on exchange rates as G3 central banks lift rates further and/or move closer to normalization.
A dovish leaning revision of Fed dots in the March SEP and European data misses may have delayed but not canceled the intensification of these rate pressures.
Buy EURAUD spot trades at 1.5880, stop at 1.5575. Marked at +0.47%.
Add longs in a 9m 1.80 EURNZD AED call with a 3m 1.80 window KO. Courtesy: JPM
FxWirePro launches Absolute Return Managed Program. For more details, visit:







