


 Yen Sinks as BOJ Rate Hike Fails to Impress Markets
 Fed Rate Hike Threatens Housing as U.S. Growth Leans on AI, Citi Says
 Bank of England Sees Surge in Higher-Risk Collateral
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 RBI Uses $10 Billion Currency Swaps to Drain Excess Rupee Liquidity
 Lithium Market Poised for Recovery Amid Supply Cuts and Rising Demand
 BOJ Set to Raise Rates to 1.25% as Inflation Risks Build
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 Stock Futures Dip as Investors Await Key Payrolls Data
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 RBA Says ASX Still Falls Short on Governance and Risk Controls


 Add as a preferred source on Google
The fact that market attention will focus less on the US labour market report today may mean that the Canadian labour market report receives more attention.
We doubt whether this will turn out to be quite so positive for CAD.
The currency is suffering as a result of the falling oil price anyway and following rising employment in August and September there is likely to be a notable countermove in October which would be expected to put pressure on CAD.
OTC outlook:
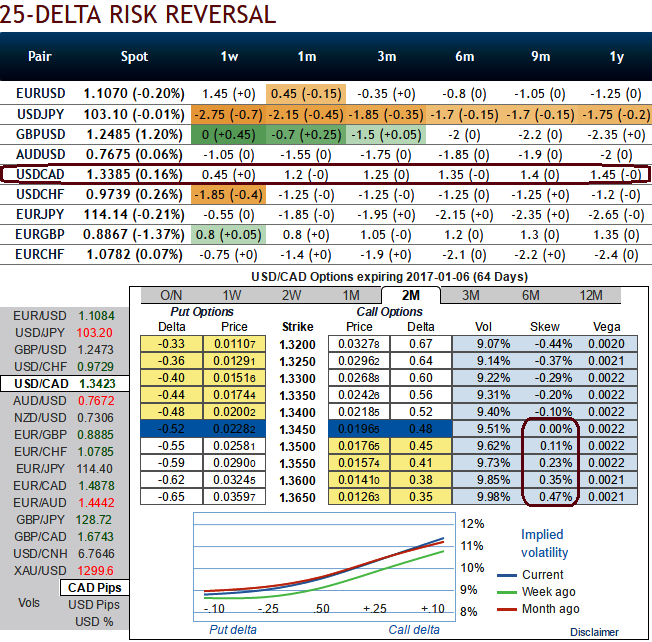
We reckon the above fundamentals seem to be reasonably addressed by hedging participants, as you can observe the risk reversal flashes for 1 and 3 months tenors, although we see neutral changes to the bullish risk sentiments, as a result, USD seems to be gaining in next 2 months tenor on recent OPEC’s announcements, on account of series of significant data events such as the US presidential polls and on the eve of Christmas where Fed’s chances of hiking can’t be disregarded.
Mounting positive skews in 2m implied volatilities suggests RKO calls on speculative grounds, the USDCAD 2-3m skew has been bid with Trump progresses in the polls, lifting it to its highest level since June 2015.
Speculative call:
Given the vol surface set-up, we see two possible option constructs to play the resulting grind higher in USDCAD but taking minor bear swings in consideration:
i) USD call/CAD put vol flies are severely depressed, much more so than ATMs (see above chart); 1*2*1 USD call/CAD put flies are therefore natural expressions of slow and steady CAD weakness.
For instance, a 3M 1.33 /1.36 with 1.39 RKI/1.39 USD call/CAD put 1*2*1 butterfly (at spot ref: 1.3342), and delivers 4 times maximum payout ratio if the RKI triggers, 9.5 times if it does not.
ii) As an alternative, one could also short shorter-dated strangles to finance the purchase of longer-dated USD call spreads and exploit the inversion of the term structure.
For instance, one could mull over shorting 1M 1.29/1.35 strangles to finance the purchase of 3M 1.33/1.36 call spreads, a nearly 75% cost savings to buying the standalone call spread.
Hedging Framework:
Strategy: 2m 3-Way Diagonal Straddle versus OTM Put
Spread ratio: (Long 1: Long 1: Short 1)
Rationale: Let’s glance on sensitivity tool for 2m IV skews would signify the interests of OTM call strikes that means the ATM calls higher likelihood of expiring in-the-money, so writing overpriced OTM puts would be a smart move to reduce hedging cost.
The execution:
Go long in USDCAD 1M at the money -0.49 delta put, and go long 2M at the money +0.51 delta call and simultaneously, Short 2W (1%) out of the money put.







